We had given a call on Rallis India limited click here for a target of Rs.160. The stock touched a high of Rs. 165.90 in today's trading session on BSE, The stock is good for long term. Short term investors can book profit.
Friday, October 11, 2013

Saturday, September 7, 2013
Mindtree Ltd: Improving Momentum! – BUY
Mindtree Ltd: Improving Momentum! – BUY
CMP Rs1,031, Target Rs1,210
CMP Rs1,031, Target Rs1,210
Deal wins, improving PES biz to help improve momentum
Mindtree's performance over the past couple of years, though not sector leading, has shown definite signs of improvement. This was supported by the sustained traction in IT services business owing to its specialized go-to-market strategy, robust client mining and more recent improvement in demand. Over past four to six months, the deal momentum has shown improvement with higher deal visibility and conversion ratios. The Product engineering (PES) business which was in the midst of restructuring and certain client specific ramp-downs too seems to have turned the corner as evidenced by better management commentary and improving discretionary spending.
Mindtree's performance over the past couple of years, though not sector leading, has shown definite signs of improvement. This was supported by the sustained traction in IT services business owing to its specialized go-to-market strategy, robust client mining and more recent improvement in demand. Over past four to six months, the deal momentum has shown improvement with higher deal visibility and conversion ratios. The Product engineering (PES) business which was in the midst of restructuring and certain client specific ramp-downs too seems to have turned the corner as evidenced by better management commentary and improving discretionary spending.
Margin outlook stable on the back of multiple levers
Margin performance of Mindtree has been impressive with a sizeable part of the up-tick over FY13 coming from operational improvements. Despite the negative impact of salary hikes, branding expenses and visa costs (total of ~350bps+), the margin expanded 530 bps supported by weak rupee, operational efficiencies and realisation improvement. Decent margin levers in the form of sustained rupee depreciation, utilisation headroom, employee pyramid and improving fixed price projects contribution should help margin performance going forward. Also, considering the relatively high offshore concentration, the negative impact of possible protectionist move in the key markets should be offset to a certain extent.
Margin performance of Mindtree has been impressive with a sizeable part of the up-tick over FY13 coming from operational improvements. Despite the negative impact of salary hikes, branding expenses and visa costs (total of ~350bps+), the margin expanded 530 bps supported by weak rupee, operational efficiencies and realisation improvement. Decent margin levers in the form of sustained rupee depreciation, utilisation headroom, employee pyramid and improving fixed price projects contribution should help margin performance going forward. Also, considering the relatively high offshore concentration, the negative impact of possible protectionist move in the key markets should be offset to a certain extent.
Attractive pick in backdrop of improving sector dynamics
Better-than-expected and well rounded Q1 FY14 results for most IT companies in our coverage as well as improving management commentary have lowered concern on the demand environment. The expectation of a stronger FY14, better deal visibility/wins as well as push back on the timing/possible impact of US immigration bill have increased sector attractiveness. This is especially true considering the weakened investment thesis for large part of the market, resultantly making IT a safe haven. Within IT, we believe, Mindtree valuations continue to be attractive at 8.5x FY15E earnings (vis-a-vis its historical average of 12x). Maintain BUY.
Better-than-expected and well rounded Q1 FY14 results for most IT companies in our coverage as well as improving management commentary have lowered concern on the demand environment. The expectation of a stronger FY14, better deal visibility/wins as well as push back on the timing/possible impact of US immigration bill have increased sector attractiveness. This is especially true considering the weakened investment thesis for large part of the market, resultantly making IT a safe haven. Within IT, we believe, Mindtree valuations continue to be attractive at 8.5x FY15E earnings (vis-a-vis its historical average of 12x). Maintain BUY.
Source: IIFL
Note : Mindtree Ltd. is a Shariah Compliant stock and hence
those
investors who are following shariah guidelines can also invest in this
stock. Its Ethical to invest in this particular stock as of today 7th September, 2013. We will update if this stock is removed from the list of
Shariah Compliant Companies in future.
Friday, August 9, 2013
Our Target Achieved in Tata Global Beverages Recommended on 29th June, 2013 Long Back
We had recommended our readers and investors to buy Tata Global Beverages in our post on 29th June, 2013 for a target of Rs. 149 which touched a high of Rs. 159.7 on 31st July, 2013. Also the stock is performing very nicely on both the indices currently. Long term investors can wait and watch for more gain since the company is technically strong and is one of the Shariah Compliant stock in Indian stock market. So keep visiting and happy investing.


And HAPPY EID to all our Readers.
Sunday, August 4, 2013
Please do not spam in Comments section on our web page, If you want to advertise on our page you are welcome!
Dear Respected Commentators,
Stock bouncers team request other bloggers who are for the sake of promoting their link on our page write repetitively same comments and sometimes which are not relevant to a particular post. This leads to inconvenience for our genuine readers who with so much interest try to understand and read our regular posts on fundamental stock market tips and investment ideas.
Please note that spamming this way will lead to poor relations between you and the author of the website. The author has always published new comments of yours, considering to be linked on our website. However commenting in bulk and on a daily basis and upon that the same comments every time is not professionalism. Hence we request you to please keep in mind our code of conduct to avoid further actions.
PLEASE READ!!!
IF YOU ARE REALLY A PROFESSIONAL BLOG WRITER THEN YOU ARE WELCOME TO ADVERTISE ON OUR WEBSITE WITH FORMAL PROCEDURES.
YOU CAN PLACE ADS IN THE FOLLOWING FORMATS
BANNER ADS AT THE TOP OF THE PAGE
BANNERS AT THE BOTTOM OF THE PAGE
BANNERS IN SIDEBARS
TEXT/LINK ADS IN SIDEBAR
ADS BETWEEN TWO POSTS
ALSO ADS IN A PARTICULAR POST OF YOUR INTEREST
If you are really interested to increase your website pageviews and want to attract genuine readers then please send your advertisement request at the following email ID
imransayed.a@gmail.com OR stockbouncers@gmail.com
Hope you understand the world of BLOGGING. Thanks for coming to us and hope you will come to us again.
STOCK BOUNCERS TEAM THANKS ALL OUR READERS WHO HAVE CONTRIBUTED IN READING ON OUR BLOG AND ENCOURAGED US TO WRITE MORE USEFUL CONTENTS BASED ON YOUR INTEREST.
HAPPY INVESTING THE ETHICAL WAY :)
Friday, July 5, 2013
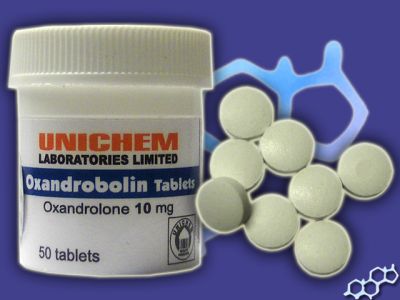
Unichem Laboratories: Attractive valuation with a strong Balance Sheet – BUY CMP Rs172, Target Rs215
Unichem laboratory (ULL), an integrated pharmaceutical company has a strong footprint in domestic
formulation market. Domestic operations contribute around 75% to total revenues. In the recent past,
the company failed to keep pace with the competitors in the domestic market but now, after the completion of restructuring activity and improving operating parameters, the company is all set to
post improvement in the margins and return ratio. We believe the rough phase for ULL is set to be over
soon; the turnaround of overseas operations along with ramp up in domestic business and cost pressure
rationalizing with incremental revenue will help ULL post robust growth.
Unichem’s four brands feature among the Top 300 Indian pharmaceutical brands and out of which two brands
are in the Top 100 (Losar H- Rs790mn- 90th Rank and Losar- Rs680mn -100th Rank). Top 10 Brands contribute
nearly 50% of the company’s domestic revenues. Domestic business will drive long term growth on leveraging
on brands. Additionally, Company is also gradually entering developed markets to leverage upon its R&D and
manufacturing capabilities. Unichem has presence in Europe through its 100% subsidiary Niche Generics having
33 products in the portfolio. It has direct sales operation in UK and Ireland and is exploring other
territories like Australia, SA and Canada. We expect this venture to add meaningful contribution to EPS
by FY14. In the US, the company has filed 29 ANDAs till date and has 15 approvals of which 9 have been
launched. We expect 2-3 filings every quarter. CRAMs business would also prove to be an interesting
opportunity for ULL.
We expect revenues to register 15% CAGR over FY13-15 and margins to expand to 15%. The company is a zero-debt company with a cumulative positive cash flow. The company is looking for acquisitions in therapy area to fill the gap in product offerings. We believe ULL’s valuation is attractive at 8.7x FY15E EPS. . We estimate the fair value of Unichem at Rs 210 and recommend BUY.
We expect revenues to register 15% CAGR over FY13-15 and margins to expand to 15%. The company is a zero-debt company with a cumulative positive cash flow. The company is looking for acquisitions in therapy area to fill the gap in product offerings. We believe ULL’s valuation is attractive at 8.7x FY15E EPS. . We estimate the fair value of Unichem at Rs 210 and recommend BUY.
Source : IIFL Ltd
Note : Unichem Laboratories is a Shariah Compliant stock with zero debt and hence those investors who are following shariah guidelines can also invest in this stock. Its Ethical to invest in this particular stock as of today 4th July, 2013. We will update if this stock is removed from the list of Shariah Compliant Companies in future.
Saturday, June 29, 2013
Tata Global Beverages Ltd – BUY CMP Rs129, Target Rs149, Upside 15.4%
Tata Global Beverages Ltd – BUY
CMP Rs129, Target Rs149, Upside 15.4%
CMP Rs129, Target Rs149, Upside 15.4%
- Correction in Kenyan tea prices augurs well for TGBL
- Rupee depreciation of ~6% yoy to drive revenues
- New business initiatives to further drive growth
- Recent price correction provides a good entry point; BUY
Tuesday, April 9, 2013
Amara Raja Batteries - A play on strong auto replacement demand
Amara Raja
Batteries Ltd (ARBL) is one of the best plays on the ensuing surge in
replacement demand for automotive batteries in the domestic market. During
FY09-12, passenger car sales in the domestic market registered a CAGR of 18.2%
and 2-wheeler sales witnessed a CAGR of 21.8%. With replacement cycle for
batteries in a passenger car of 30-36 months and that of a switch-start 2-wheeler
of 24-30 months, substantial jump in replacement demand can be seen in the near
future. As compared to past, 2-wheeler battery replacement market is likely to
increase in size. This can be mainly attributed to the rising proportion of
switch-start 2-wheelers in the domestic sales.

Steady
increase in automotive market share
ARBL has
gained a strong foothold in the replacement market for the automotive with a
steady increase in market share in the segment. Even with the OEMs, the company
has been able to get into its fold most incumbent players and is in discussions
to enter into tie-ups with new entrants.

Industrial
segment to add to momentum
The
industrial segment is mainly driven by demand for UPS led by investments in IT
industry and towers in the telecom segments. Battery demand in the UPS segment,
which has witnessed a 15% growth, is expected to continue given that
investments in computerization by India Inc has been on a rise. While pace of
new addition of new telecom towers has slowed down, replacement of batteries in
the existing towers is due which will keep demand growth from the segment
robust.

Strong
revenue and profit growth, attractive valuations
ARBL, to capture
these growth opportunities is expanding capacities in all segments by nearly
50% by H2 FY15. The company has been performing better than Exide in the past
few quarters on all counts. This has triggered a re-rating in the stock. We
expect the performance to continue on both revenue and profitability fronts with
estimates of a revenue and PAT CAGR of 22%
and 26% respectively between FY12-15E.

Courtesy and Source : IIFL Ltd.
Note : Amara Raja Batteries Ltd is a Shariah Compliant stock and hence those investors who are following shariah guidelines can also invest in this stock. Its Ethical to invest in this particular stock as of today 9th April, 2013. We will update if this stock is removed from the list of Shariah Compliant Companies.
Note : Amara Raja Batteries Ltd is a Shariah Compliant stock and hence those investors who are following shariah guidelines can also invest in this stock. Its Ethical to invest in this particular stock as of today 9th April, 2013. We will update if this stock is removed from the list of Shariah Compliant Companies.
Subscribe to:
Posts (Atom)